Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
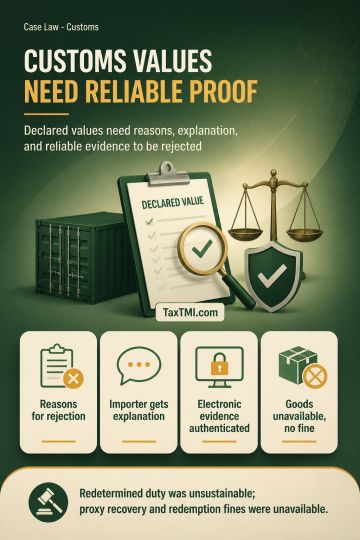
Rule 12 permits rejection of declared customs value only where there is reason to doubt its truth or accuracy, the importer has an opportunity to explain the price, and valuation follows the prescribed method, including contemporaneous import values where relevant. Unsupported intelligence and recovered documents did not establish undervaluation, rendering redetermination and differential duty unsustainable. Electronic data, messages, emails and invoices required statutory certification and reliable authentication; unauthenticated material could not prove undervaluation. Each IEC holder filing its own bill of entry remained the importer liable for duty, preventing recovery from an alleged proxy importer. Goods unavailable for confiscation could not attract confiscation or redemption fine.
Rule 12 permits rejection of declared customs value only where there is reason to doubt its truth or accuracy, the importer has an opportunity to explain the price, and valuation follows the prescribed method, including contemporaneous import values where relevant. Unsupported intelligence and recovered documents did not establish undervaluation, rendering redetermination and differential duty unsustainable. Electronic data, messages, emails and invoices required statutory certification and reliable authentication; unauthenticated material could not prove undervaluation. Each IEC holder filing its own bill of entry remained the importer liable for duty, preventing recovery from an alleged proxy importer. Goods unavailable for confiscation could not attract confiscation or redemption fine.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918