Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
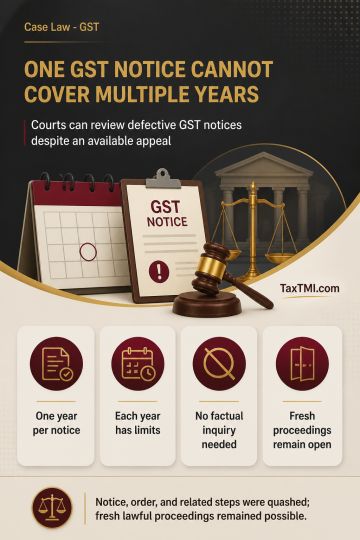
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
FERA penalty quantification must be reasoned, reasonable and proportionate to the contravention; the statutory maximum under Section 50 does not by itself justify the amount imposed. Where certain export-realisation contraventions were excluded and an RBI write-off was noted, retaining the original penalty without explaining its basis was disproportionate. A finding that the penalty was not harsh or excessive, without articulated quantification reasons, was insufficient. The penalty was therefore set aside and redetermined at a lower amount, with the appeal partly allowed.
FERA penalty quantification must be reasoned, reasonable and proportionate to the contravention; the statutory maximum under Section 50 does not by itself justify the amount imposed. Where certain export-realisation contraventions were excluded and an RBI write-off was noted, retaining the original penalty without explaining its basis was disproportionate. A finding that the penalty was not harsh or excessive, without articulated quantification reasons, was insufficient. The penalty was therefore set aside and redetermined at a lower amount, with the appeal partly allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916