Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
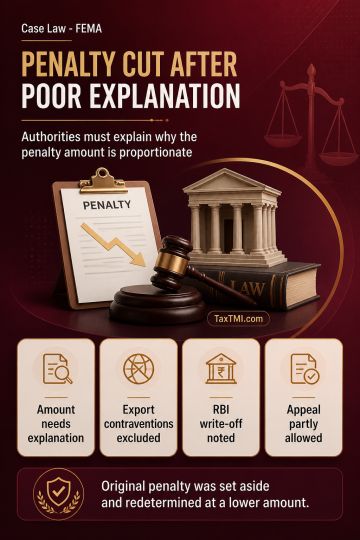
FERA penalty quantification must be reasoned, reasonable and proportionate to the contravention; the statutory maximum under Section 50 does not by itself justify the amount imposed. Where certain export-realisation contraventions were excluded and an RBI write-off was noted, retaining the original penalty without explaining its basis was disproportionate. A finding that the penalty was not harsh or excessive, without articulated quantification reasons, was insufficient. The penalty was therefore set aside and redetermined at a lower amount, with the appeal partly allowed.
FERA penalty quantification must be reasoned, reasonable and proportionate to the contravention; the statutory maximum under Section 50 does not by itself justify the amount imposed. Where certain export-realisation contraventions were excluded and an RBI write-off was noted, retaining the original penalty without explaining its basis was disproportionate. A finding that the penalty was not harsh or excessive, without articulated quantification reasons, was insufficient. The penalty was therefore set aside and redetermined at a lower amount, with the appeal partly allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916