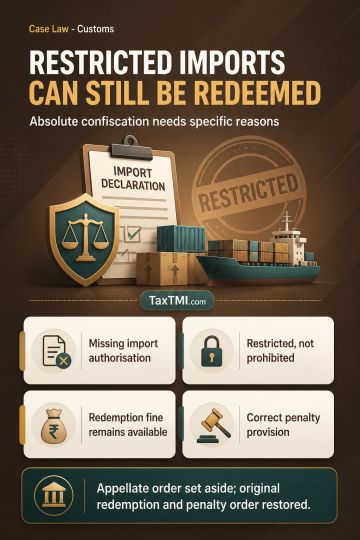
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
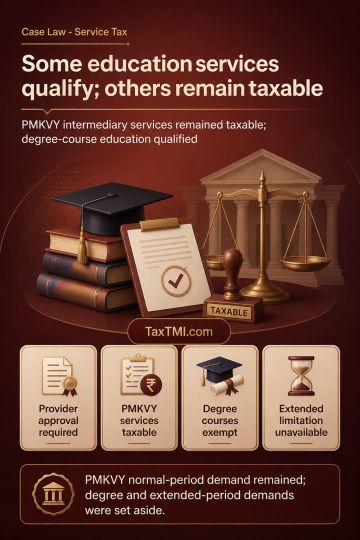
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916