Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
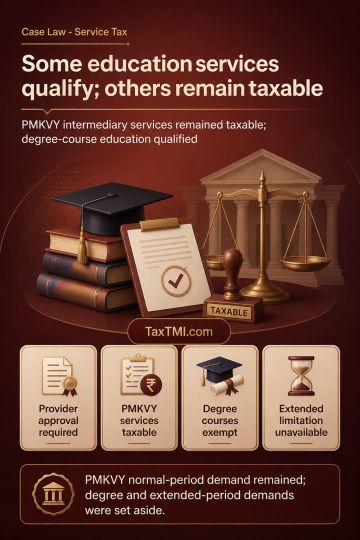
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI