Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
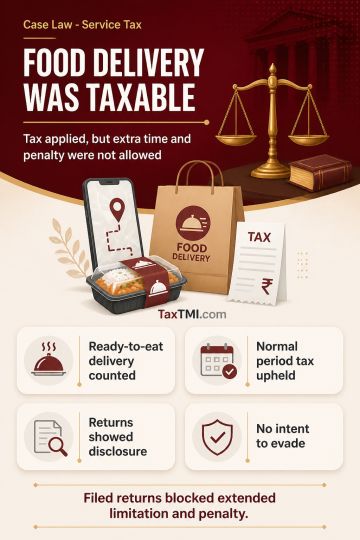
Free home delivery of ready-to-eat food, involving preparation at the supplier's premises and delivery at a customer-specified time and place, was treated as a taxable service with a significant service element. From July 2012, supplying food for human consumption in this manner fell within declared services and also within the earlier concept of outdoor catering. Service tax was consequently sustainable for the normal limitation period. The extended limitation period and related penalty were not sustainable because the supplier was registered, filed ST-3 returns, paid service tax, and the allegations arose from its own records, with no evidence of suppression intended to evade tax.
Free home delivery of ready-to-eat food, involving preparation at the supplier's premises and delivery at a customer-specified time and place, was treated as a taxable service with a significant service element. From July 2012, supplying food for human consumption in this manner fell within declared services and also within the earlier concept of outdoor catering. Service tax was consequently sustainable for the normal limitation period. The extended limitation period and related penalty were not sustainable because the supplier was registered, filed ST-3 returns, paid service tax, and the allegations arose from its own records, with no evidence of suppression intended to evade tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918