Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
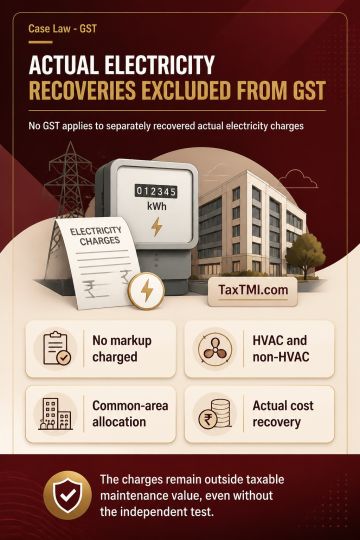
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921