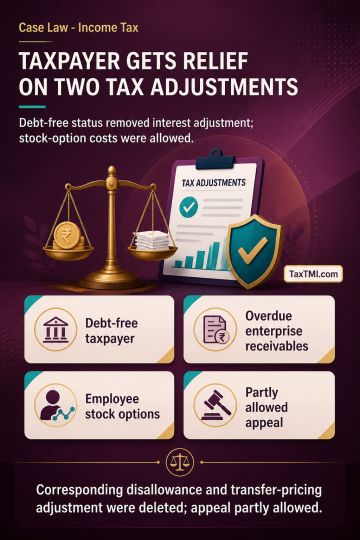
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
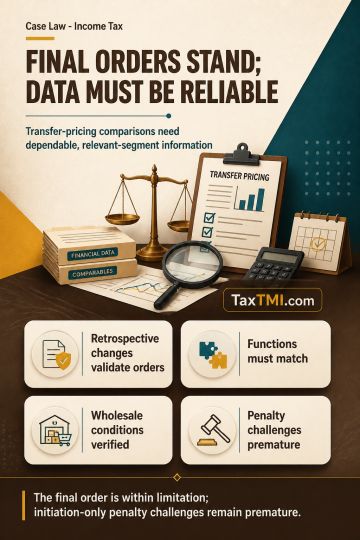
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
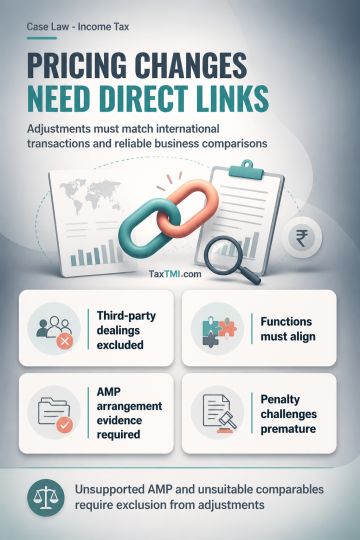
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
Page of 4931
Press 'Enter' after typing page number.
1941 to 1960 of 98613 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
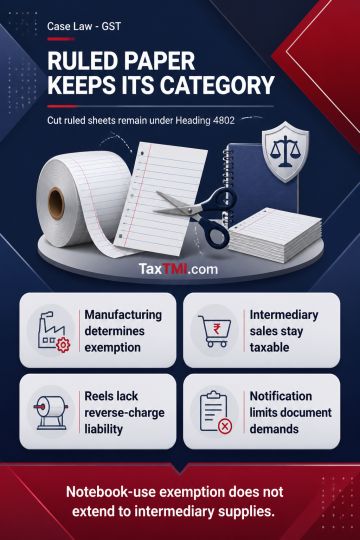
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931