Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
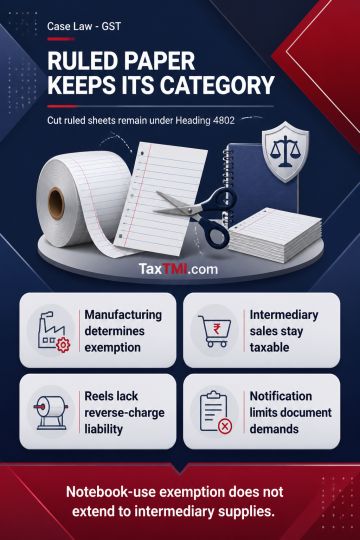
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916