Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
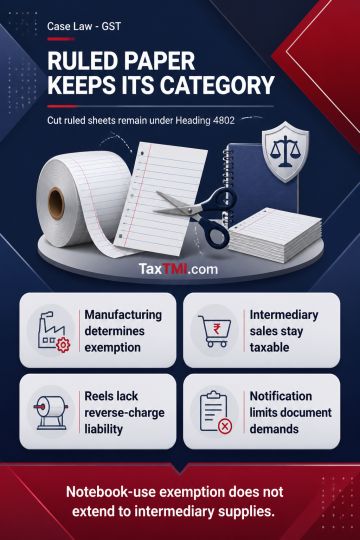
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Ruled or lined loose paper sheets produced by cutting uncoated paper remain within Heading 4802, rather than Heading 4820, because loose sheets cut to size are excluded from the finished-stationery heading. Paper is classified under tariff item 48026190 in rolls and 48026290 in sheets. The end-use exemption for paper used in specified notebooks depends on actual use by the manufacturer; supplies through intermediaries remain independently taxable. Recipients of uncoated paper reels have no reverse-charge liability because the goods are not notified for reverse charge, while input tax credit remains subject to statutory conditions. Documentary requirements cannot be imposed where the exemption notification does not prescribe them.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI