Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Statutory return periodicity governed tax payment due dates, invalidating interest and preserving writ relief where no appeal lay.
    Depository SFT reporting requires half-yearly transaction data, capital-gain classification, secure filing, and corrections for inaccurate submissions...
    Mutual fund capital-gains reporting requires RTAs to submit validated half-yearly SFT data and correct inaccuracies through revised statements.
    Due diligence in insolvency requires closer inquiry and Adjudicating Authority applications where CIRP or liquidation appears fraudulent or malicious.
    Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
    Supplier tax-payment condition for input tax credit faces constitutional challenge, while the High Court ruling remains stayed.
    GST portal access for nil demand orders enables regular statutory appeals where disputed tax was deposited under protest.
    Foundational facts in fraud-based GST notices are mandatory; unsupported fake-invoice input tax credit allegations cannot sustain proceedings.
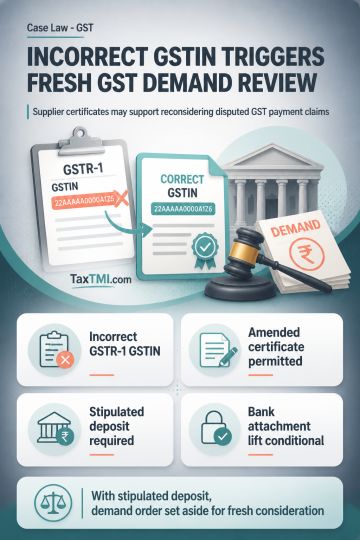
    Supplier certificates supporting GST payment can require fresh demand review when GSTR-1 contains an incorrect GSTIN.
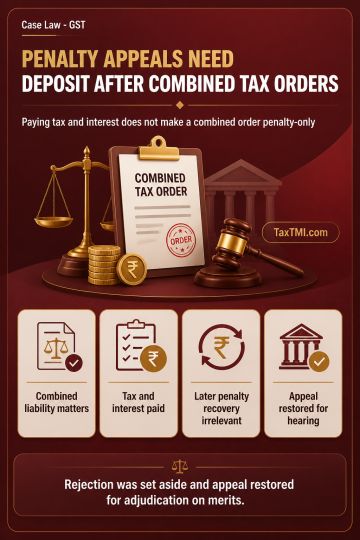
    Statutory pre-deposit exemption applies only to standalone penalty demands, not composite orders where tax and interest were later paid.
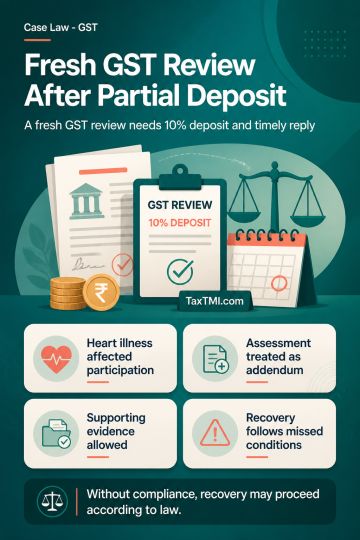
    Conditional de novo GST adjudication permits reassessment after partial pre-deposit, reply to the show-cause notice, and supporting evidence.
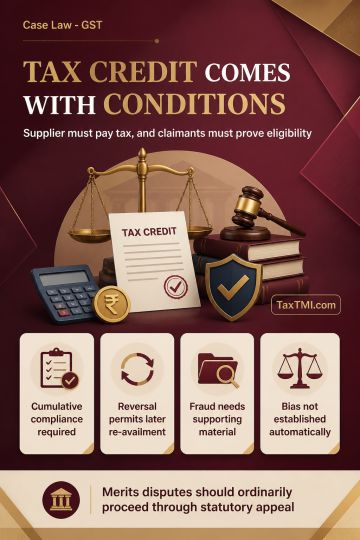
    Input tax credit conditions require supplier tax payment, while fraud allegations and adjudication merits proceed through statutory appeal.
    Interest waiver requires a pre-existing jurisdictional ruling and payment of principal tax; excess demand interest may be refunded.
    Penalty jurisdiction under cash loan restrictions cannot support revision where assessments predate the Assessing Officer's authority.
    Obsolete inventory valuation at net realisable value stands where the Revenue lacks evidence of a higher recoverable amount.
    Survey surrender income from business cash and stock discrepancies attracts normal business tax rates, not enhanced taxation retrospectively.
    Recorded business receipts cannot be treated as unexplained money when cash deposits remain within disclosed book balances.
    Deeming fiction for depreciable assets does not exclude sale profits from book profit for partners' remuneration ceilings.
    Share-Premium Taxation Cannot Apply Retroactively; Composite Share Receipts Require Component-Wise Verification Under Applicable Credit Rules.
    Documentary proof of inherited jewellery defeats unexplained-income additions, while duplicate HUF brokerage lacks capital-gains deductibility.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

End-use-based GST exemption for uncoated paper and paperboard...

End-use GST exemption for uncoated paper depends on proven manufacture of specified books, while other uses remain taxable.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST September 8, 2026 Case Laws AAR
End-use-based GST exemption for uncoated paper and paperboard under tariff heading 4802 depends on established actual use in manufacturing exercise books, graph books, laboratory notebooks or notebooks. Classification turns on actual use rather than intended use, paper grade or specifications; supplies used for other purposes remain taxable. Questions on supplier verification, documentary requirements and liability for a purchaser's misuse fall outside an advance ruling on notification applicability where the notification contains no such mechanisms. Revised Central and corresponding State GST rate entries take effect from 22.09.2025, leaving no stated ambiguity on the rate transition date.

Topics

Acts Income Tax