Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
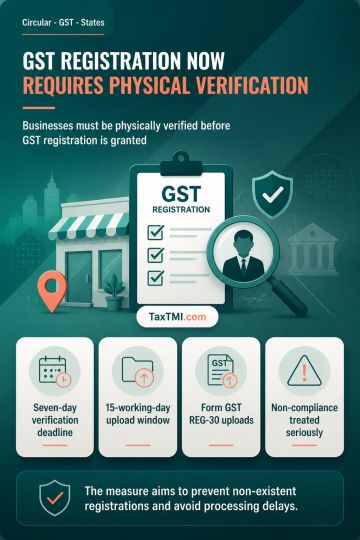
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Page of 4920
Press 'Enter' after typing page number.
1521 to 1540 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
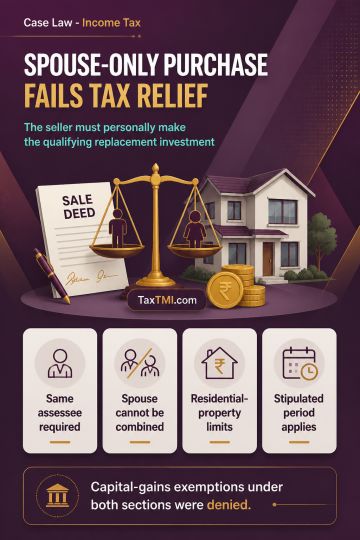
Section 54F applies only where the transferred long-term capital asset is not a residential house; exemption is therefore unavailable when both the original and replacement assets are residential properties. Section 54 requires the same assessee to sell the original residential property and purchase or construct the new property within the stipulated period. Investment solely in a spouse's name does not satisfy this requirement, as spouses are distinct legal entities and the husband's sale cannot be clubbed with the wife's sole acquisition. Consequently, capital-gains exemption under sections 54F and 54 was denied.
Section 54F applies only where the transferred long-term capital asset is not a residential house; exemption is therefore unavailable when both the original and replacement assets are residential properties. Section 54 requires the same assessee to sell the original residential property and purchase or construct the new property within the stipulated period. Investment solely in a spouse's name does not satisfy this requirement, as spouses are distinct legal entities and the husband's sale cannot be clubbed with the wife's sole acquisition. Consequently, capital-gains exemption under sections 54F and 54 was denied.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920