Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
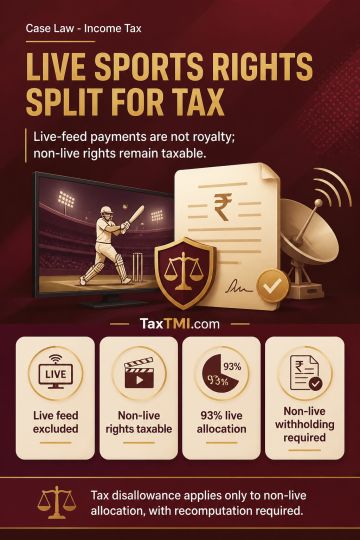
Live sports broadcasting rights do not transfer copyright in a live telecast capable of generating royalty income; therefore, consideration attributable to the live feed is not royalty. Repeat or other non-live telecast rights remain within royalty treatment. Composite media-rights consideration is apportioned using established viewership data: 93% for live broadcasting and 7% for non-live broadcasting. Tax-disallowance for failure to deduct tax applies only to the payment allocated to non-live rights, requiring consequential recomputation of the disallowance.
Live sports broadcasting rights do not transfer copyright in a live telecast capable of generating royalty income; therefore, consideration attributable to the live feed is not royalty. Repeat or other non-live telecast rights remain within royalty treatment. Composite media-rights consideration is apportioned using established viewership data: 93% for live broadcasting and 7% for non-live broadcasting. Tax-disallowance for failure to deduct tax applies only to the payment allocated to non-live rights, requiring consequential recomputation of the disallowance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918