Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Internal comparable uncontrolled transactions should be...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
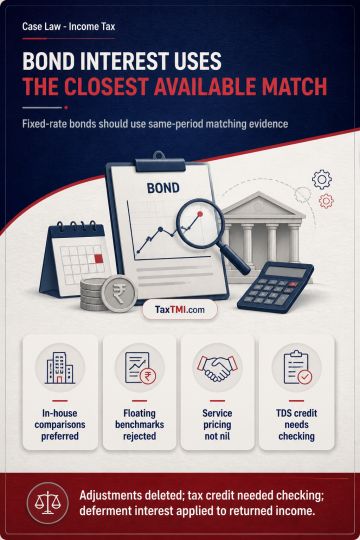
Internal comparable uncontrolled transactions should be preferred over external comparables for benchmarking fixed-rate Masala Bond interest where they arise in the same period and offer greater comparability. A floating external benchmark is inconsistent with the strict comparability required under the CUP method, resulting in deletion of the related transfer-pricing adjustment. Specialised operational and maintenance services received from an associated enterprise are not shareholder activities; where receipt and need are evidenced, their arm's length price cannot be fixed at nil without comparable uncontrolled transactions. The related adjustment was deleted. TDS credit requires factual verification, while interest for advance-tax deferment is chargeable only on returned income, not assessed income.
Internal comparable uncontrolled transactions should be preferred over external comparables for benchmarking fixed-rate Masala Bond interest where they arise in the same period and offer greater comparability. A floating external benchmark is inconsistent with the strict comparability required under the CUP method, resulting in deletion of the related transfer-pricing adjustment. Specialised operational and maintenance services received from an associated enterprise are not shareholder activities; where receipt and need are evidenced, their arm's length price cannot be fixed at nil without comparable uncontrolled transactions. The related adjustment was deleted. TDS credit requires factual verification, while interest for advance-tax deferment is chargeable only on returned income, not assessed income.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI