Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
Page of 4931
Press 'Enter' after typing page number.
1941 to 1960 of 98613 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Revision proceedings require the designated statutory authority...
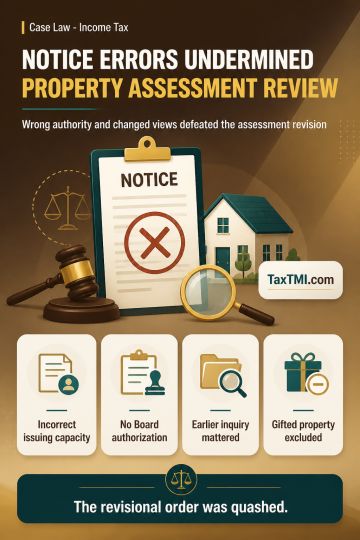
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Revision proceedings require the designated statutory authority to issue the notice in the correct official capacity. A Chief Commissioner issuing a notice as Principal Commissioner, without an express Board order authorising exercise of that function, lacks jurisdiction and invalidates the resulting revision. Revision for notional annual letting value of professionally used properties also cannot rest on a change of opinion where the Assessing Officer examined ownership, use and house-property treatment and adopted a plausible view. Explanation 2 to section 263 does not apply where genuine inquiry and verification occurred. Properties transferred by gift are not assessable in the transferor's hands. The revisional order was quashed.
Revision proceedings require the designated statutory authority to issue the notice in the correct official capacity. A Chief Commissioner issuing a notice as Principal Commissioner, without an express Board order authorising exercise of that function, lacks jurisdiction and invalidates the resulting revision. Revision for notional annual letting value of professionally used properties also cannot rest on a change of opinion where the Assessing Officer examined ownership, use and house-property treatment and adopted a plausible view. Explanation 2 to section 263 does not apply where genuine inquiry and verification occurred. Properties transferred by gift are not assessable in the transferor's hands. The revisional order was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931