Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
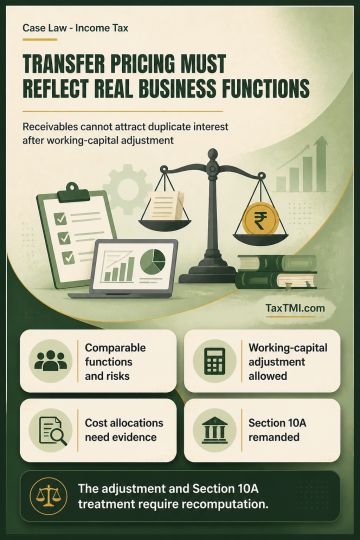
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
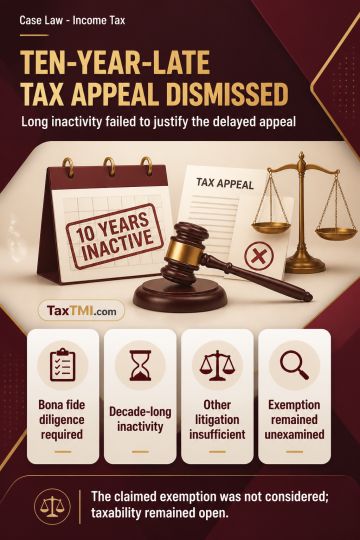
Condonation of delay requires sufficient cause founded on bona fide diligence and circumstances beyond the litigant's control. Voluntarily offering a receipt to tax, accepting the intimation, and remaining inactive for more than a decade did not meet that standard; awaiting litigation concerning another entity's registration, mistaken belief about registration, later legal developments, difficulty locating records, and professional consultation were insufficient. The inordinate delay in filing the first appeal was therefore not condoned, and the appeal was dismissed without considering the claimed exemption. The taxability of the one-time benefit remained open.
Condonation of delay requires sufficient cause founded on bona fide diligence and circumstances beyond the litigant's control. Voluntarily offering a receipt to tax, accepting the intimation, and remaining inactive for more than a decade did not meet that standard; awaiting litigation concerning another entity's registration, mistaken belief about registration, later legal developments, difficulty locating records, and professional consultation were insufficient. The inordinate delay in filing the first appeal was therefore not condoned, and the appeal was dismissed without considering the claimed exemption. The taxability of the one-time benefit remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923