Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
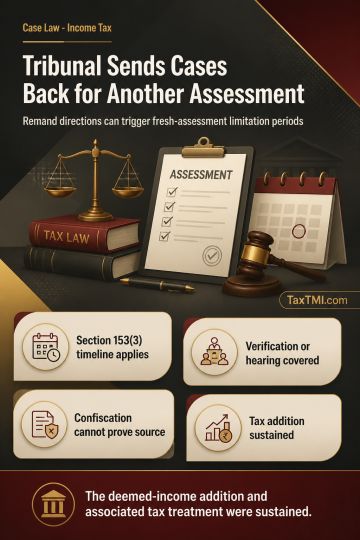
Section 153(5) applies where effect can be given without making a fresh assessment or reassessment. Where a Tribunal remand requires the Assessing Officer to undertake fresh consideration, the limitation period for fresh assessment under section 153(3) applies; the proviso to section 153(5) also covers matters requiring verification or an opportunity of hearing. Foreign currency may be treated as unexplained money where the taxpayer provides inconsistent explanations and fails to prove its source through satisfactory evidence, including acquisition from authorised dealers. FEMA confiscation for excess possession does not by itself establish the currency's source for income-tax purposes. The addition as deemed income and the associated tax treatment were sustained.
Section 153(5) applies where effect can be given without making a fresh assessment or reassessment. Where a Tribunal remand requires the Assessing Officer to undertake fresh consideration, the limitation period for fresh assessment under section 153(3) applies; the proviso to section 153(5) also covers matters requiring verification or an opportunity of hearing. Foreign currency may be treated as unexplained money where the taxpayer provides inconsistent explanations and fails to prove its source through satisfactory evidence, including acquisition from authorised dealers. FEMA confiscation for excess possession does not by itself establish the currency's source for income-tax purposes. The addition as deemed income and the associated tax treatment were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918