Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
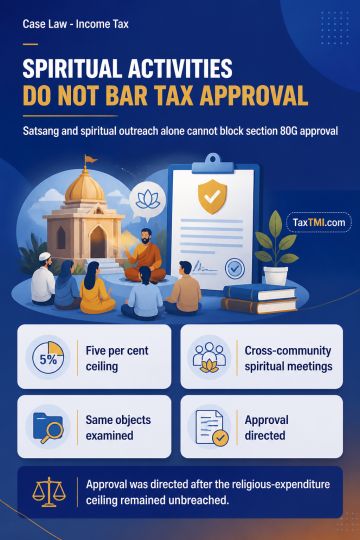
Approval under section 80G for a religious-cum-charitable trust cannot be denied merely because it conducts satsang or disseminates spiritual knowledge. Expenditure on those activities remained below the five per cent ceiling for religious expenditure under Explanation (3) to section 80G. Meetings intended to spread spiritual knowledge across communities are not, by themselves, religious activities; satsang is similarly not religious unless expenditure concerns a particular deity or related activity. Where registration under section 12AB has been granted after examining the same objects, section 80G approval must follow absent breach of its specific statutory conditions. Approval was directed to be granted.
Approval under section 80G for a religious-cum-charitable trust cannot be denied merely because it conducts satsang or disseminates spiritual knowledge. Expenditure on those activities remained below the five per cent ceiling for religious expenditure under Explanation (3) to section 80G. Meetings intended to spread spiritual knowledge across communities are not, by themselves, religious activities; satsang is similarly not religious unless expenditure concerns a particular deity or related activity. Where registration under section 12AB has been granted after examining the same objects, section 80G approval must follow absent breach of its specific statutory conditions. Approval was directed to be granted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916