Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
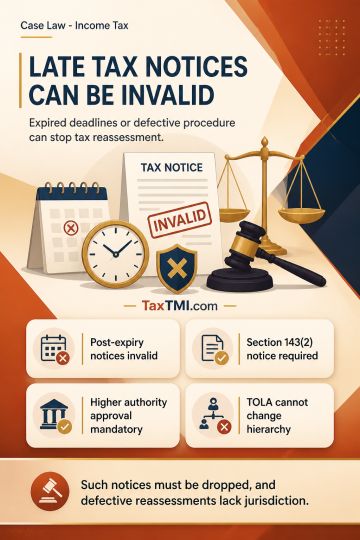
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916