Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
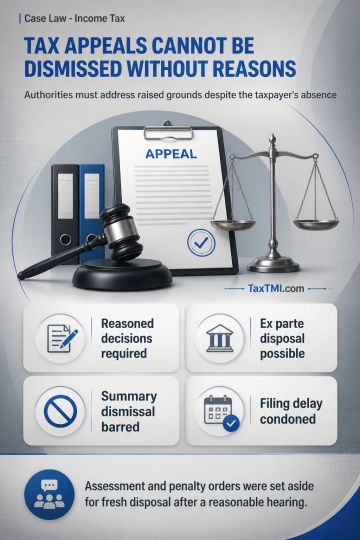
Appellate authorities must decide appeals on their merits and address the grounds raised, even where the assessee does not participate after notice. Ex parte disposal may rest on the material on record, but summary dismissal for non-prosecution without a reasoned, speaking adjudication is impermissible. Appellate orders concerning assessment and penalty matters for three assessment years were set aside for fresh disposal after reasonable hearing opportunity. A filing delay caused by failure to serve an appellate order through the physical mode requested by the assessee warranted condonation under a justice-oriented, liberal approach.
Appellate authorities must decide appeals on their merits and address the grounds raised, even where the assessee does not participate after notice. Ex parte disposal may rest on the material on record, but summary dismissal for non-prosecution without a reasoned, speaking adjudication is impermissible. Appellate orders concerning assessment and penalty matters for three assessment years were set aside for fresh disposal after reasonable hearing opportunity. A filing delay caused by failure to serve an appellate order through the physical mode requested by the assessee warranted condonation under a justice-oriented, liberal approach.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916