Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
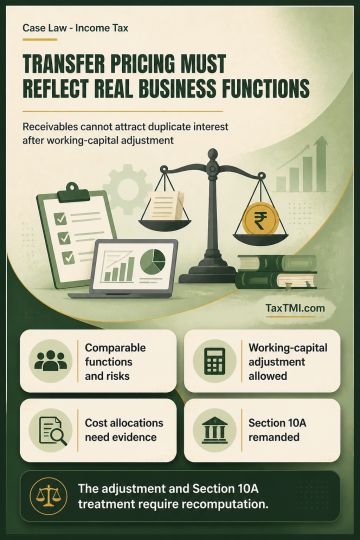
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Transfer of title in goods, including deemed sales under works...
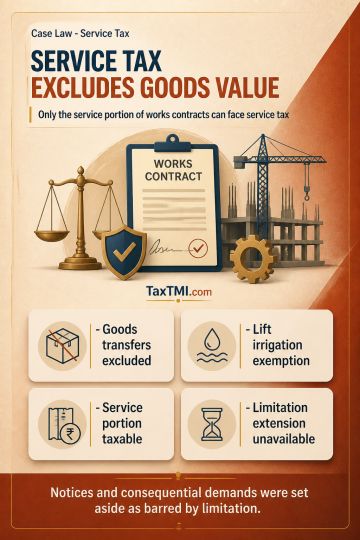
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot apply.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer of title in goods, including deemed sales under works contracts, falls outside service tax; tax applies only to the service portion, and valuation must exclude goods on which sales tax or VAT is payable. Accordingly, service-tax demands based on the sale-of-goods component of lift irrigation and supply-and-installation contracts were unsustainable. Lift irrigation works supplied to a government-established and controlled body performing municipal functions qualified for exemption as services to a governmental authority. Extended limitation required wilful suppression or another specified positive act and could not rest solely on an interpretative exemption claim, Form 26AS information, or alleged non-payment. The notices and consequential demands were barred by limitation and set aside.
Transfer of title in goods, including deemed sales under works contracts, falls outside service tax; tax applies only to the service portion, and valuation must exclude goods on which sales tax or VAT is payable. Accordingly, service-tax demands based on the sale-of-goods component of lift irrigation and supply-and-installation contracts were unsustainable. Lift irrigation works supplied to a government-established and controlled body performing municipal functions qualified for exemption as services to a governmental authority. Extended limitation required wilful suppression or another specified positive act and could not rest solely on an interpretative exemption claim, Form 26AS information, or alleged non-payment. The notices and consequential demands were barred by limitation and set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918