Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
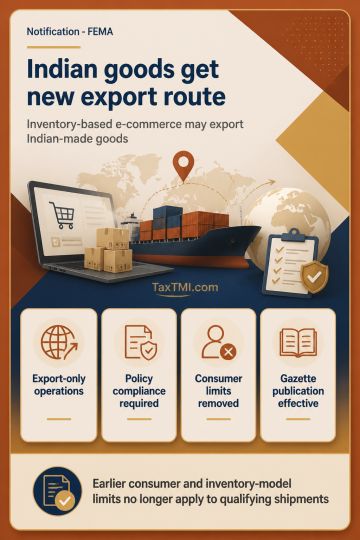
Schedule I now permits e-commerce entities to operate an inventory-based e-commerce model exclusively for exporting goods or products manufactured or produced in India. Such exports must comply with the Foreign Trade Policy 2023, the Handbook of Procedures, and the Foreign Exchange Management (Export of Goods and Services) Regulations, 2015. For exports permitted under this new entry, the existing restrictions on business-to-consumer transactions and inventory-based e-commerce under entries 15.2.1 to 15.2.4 do not apply. The amendment takes effect from its publication in the Official Gazette.
Schedule I now permits e-commerce entities to operate an inventory-based e-commerce model exclusively for exporting goods or products manufactured or produced in India. Such exports must comply with the Foreign Trade Policy 2023, the Handbook of Procedures, and the Foreign Exchange Management (Export of Goods and Services) Regulations, 2015. For exports permitted under this new entry, the existing restrictions on business-to-consumer transactions and inventory-based e-commerce under entries 15.2.1 to 15.2.4 do not apply. The amendment takes effect from its publication in the Official Gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916