Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
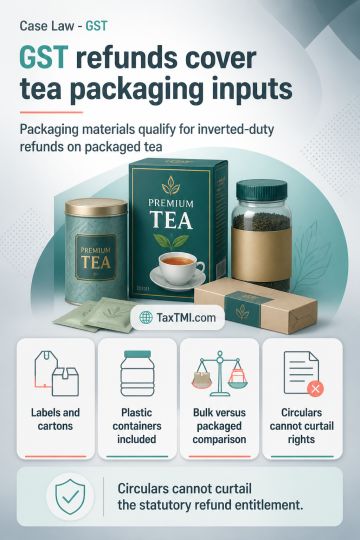
Refund of unutilised input tax credit under an inverted duty structure extends to packing materials, labels, cartons and plastic containers used to market packaged tea. Section 54(3)(ii) treats such materials as inputs and does not distinguish between principal and ancillary inputs; comparison of bulk tea and packaged tea without considering packaging inputs is therefore incorrect. Circular No. 135/5/2020-GST addresses credit accumulation caused by a rate reduction on the same goods at different times and does not apply where bulk and packaged tea bear the same tax rate. Administrative circulars cannot add to or curtail the statutory refund entitlement.
Refund of unutilised input tax credit under an inverted duty structure extends to packing materials, labels, cartons and plastic containers used to market packaged tea. Section 54(3)(ii) treats such materials as inputs and does not distinguish between principal and ancillary inputs; comparison of bulk tea and packaged tea without considering packaging inputs is therefore incorrect. Circular No. 135/5/2020-GST addresses credit accumulation caused by a rate reduction on the same goods at different times and does not apply where bulk and packaged tea bear the same tax rate. Administrative circulars cannot add to or curtail the statutory refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918