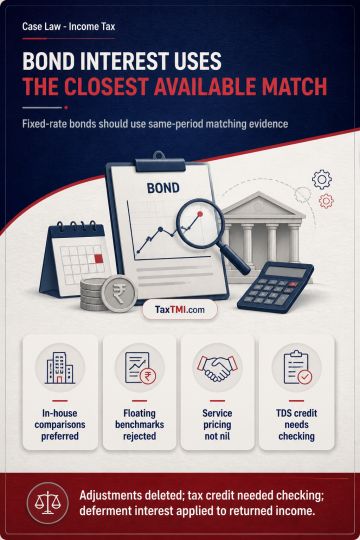
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Transfer of an assessment case under section 127 by a Joint Commissioner lacking statutory power is jurisdictionally invalid. An assessee must also be afforded an opportunity of hearing before transfer between Assessing Officers. Participation in subsequent assessment proceedings, or failure to object within thirty days, cannot cure a transfer made by an incompetent authority. Consequently, an assessment made by the transferee Assessing Officer is non est, and a penalty for furnishing inaccurate particulars founded on that assessment cannot survive. The assessment and consequential penalty were quashed.
Transfer of an assessment case under section 127 by a Joint Commissioner lacking statutory power is jurisdictionally invalid. An assessee must also be afforded an opportunity of hearing before transfer between Assessing Officers. Participation in subsequent assessment proceedings, or failure to object within thirty days, cannot cure a transfer made by an incompetent authority. Consequently, an assessment made by the transferee Assessing Officer is non est, and a penalty for furnishing inaccurate particulars founded on that assessment cannot survive. The assessment and consequential penalty were quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916