Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Page of 4918
Press 'Enter' after typing page number.
1641 to 1660 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
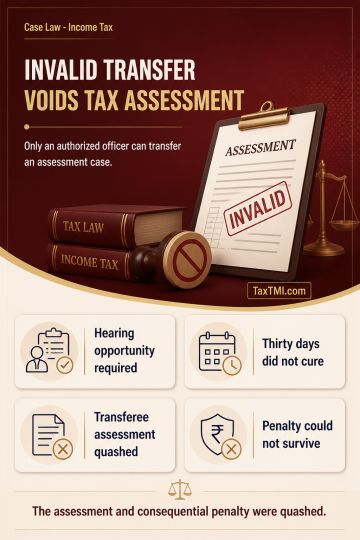
Transfer of an assessment case under section 127 by a Joint Commissioner lacking statutory power is jurisdictionally invalid. An assessee must also be afforded an opportunity of hearing before transfer between Assessing Officers. Participation in subsequent assessment proceedings, or failure to object within thirty days, cannot cure a transfer made by an incompetent authority. Consequently, an assessment made by the transferee Assessing Officer is non est, and a penalty for furnishing inaccurate particulars founded on that assessment cannot survive. The assessment and consequential penalty were quashed.
Transfer of an assessment case under section 127 by a Joint Commissioner lacking statutory power is jurisdictionally invalid. An assessee must also be afforded an opportunity of hearing before transfer between Assessing Officers. Participation in subsequent assessment proceedings, or failure to object within thirty days, cannot cure a transfer made by an incompetent authority. Consequently, an assessment made by the transferee Assessing Officer is non est, and a penalty for furnishing inaccurate particulars founded on that assessment cannot survive. The assessment and consequential penalty were quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918