Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
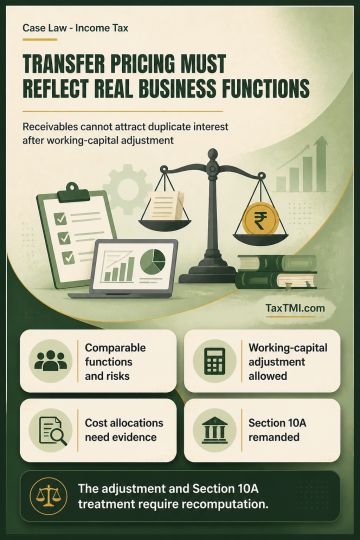
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
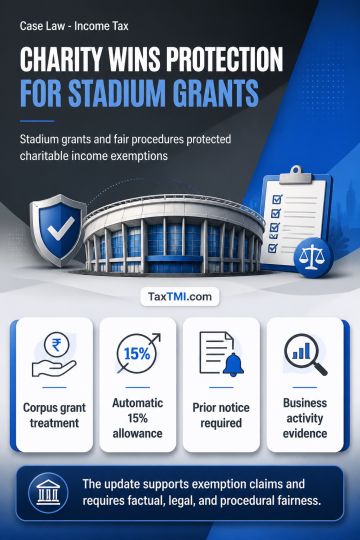
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918