Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
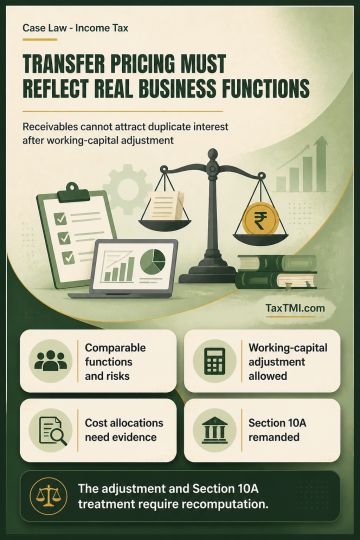
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
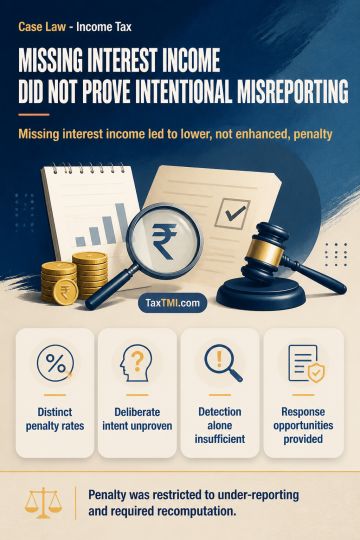
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918