Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
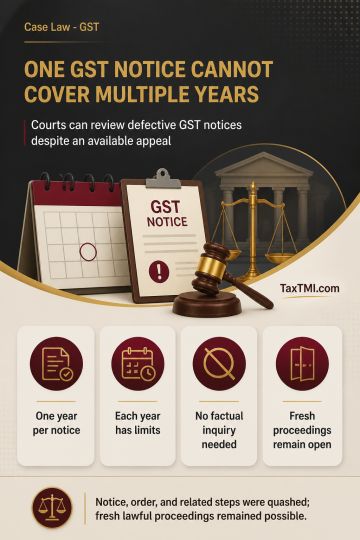
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
Penalty under section 271(1)(c) is not leviable where a taxpayer fully discloses a slump-sale transaction, consideration and negative net worth, but computes capital gains by treating negative net worth as nil on a bona fide legal interpretation. A claim that is ultimately unsustainable does not amount to furnishing inaccurate particulars merely because a quantum addition is sustained or not contested. Divergent Tribunal views and admission of a substantial question of law support the conclusion that the treatment of negative net worth was genuinely debatable. The penalty deletion was sustained and the Revenue's appeal failed.
Penalty under section 271(1)(c) is not leviable where a taxpayer fully discloses a slump-sale transaction, consideration and negative net worth, but computes capital gains by treating negative net worth as nil on a bona fide legal interpretation. A claim that is ultimately unsustainable does not amount to furnishing inaccurate particulars merely because a quantum addition is sustained or not contested. Divergent Tribunal views and admission of a substantial question of law support the conclusion that the treatment of negative net worth was genuinely debatable. The penalty deletion was sustained and the Revenue's appeal failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916