Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
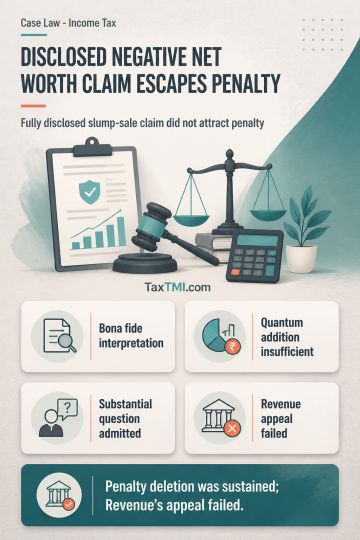
Penalty under section 271(1)(c) is not leviable where a taxpayer fully discloses a slump-sale transaction, consideration and negative net worth, but computes capital gains by treating negative net worth as nil on a bona fide legal interpretation. A claim that is ultimately unsustainable does not amount to furnishing inaccurate particulars merely because a quantum addition is sustained or not contested. Divergent Tribunal views and admission of a substantial question of law support the conclusion that the treatment of negative net worth was genuinely debatable. The penalty deletion was sustained and the Revenue's appeal failed.
Penalty under section 271(1)(c) is not leviable where a taxpayer fully discloses a slump-sale transaction, consideration and negative net worth, but computes capital gains by treating negative net worth as nil on a bona fide legal interpretation. A claim that is ultimately unsustainable does not amount to furnishing inaccurate particulars merely because a quantum addition is sustained or not contested. Divergent Tribunal views and admission of a substantial question of law support the conclusion that the treatment of negative net worth was genuinely debatable. The penalty deletion was sustained and the Revenue's appeal failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918