Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    E-way bill vehicle mismatch supports tax-evasion inference and sustains penalties where Part B lacks timely correction.
    Tax withholding on non-resident payments requires Indian taxability; no Section 201 default arises where income is not chargeable.
    Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
    Limitation for consequential assessments requires timely verification orders; delayed orders are invalid and returned income stands accepted.
    Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
    Prior show-cause notice for unexplained-money additions protects hearing rights; unsupported assessment and penalty notices were quashed.
    Prepaid tax credit and refund remain available when a reassessment return is treated as a regular return.
    Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
    Territorial and subject-matter jurisdiction governs charitable registration cancellation; centralised assessment alone cannot validate cancellation au...
    Goodwill depreciation and TDS credit depend on real slump-sale consideration and the year corresponding income is assessable.
    Non-monetary business benefits from below-value land acquisitions are taxable, while deductions remain limited to actual cost.
    Project-completion accounting cannot be rejected without accounting defects or evidence of undisclosed flat-sale consideration.
    Binding jurisdictional precedent limits return-processing disallowances and supports rectification for mistakes apparent from the record.
    Misreporting-based tax penalty excludes bona fide explanation protection where inadmissible deductions caused under-reporting of income.
    Estimated cash-deposit additions alone cannot establish concealment for penalty, resulting in deletion of the levy.
    TNMM aggregation prevents separate benchmarking of inseparable IT support costs, while debt-free receivables and research deductions receive relief.
    Transactional Net Margin Method prevents separate nil pricing of closely linked selling commission already included in segmental operating costs.
    Third-party seized records require corroboration, while Rule 8D cannot increase minimum alternate tax book profit.
    Unauthorised gold import restrictions classify goods as prohibited, attracting the enhanced customs penalty regime despite citation defects.
    Target Plus Scheme broad nexus allows grouped input linkage, while absent intent defeats extended customs limitation and penalties.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Business dependence on regulatory affairs and compliance...

Business Dependence Establishes Associated Enterprise Status; Domestic Tested Party and Fresh Regulatory Affairs Benchmarking Required

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 7, 2026 Case Laws AT
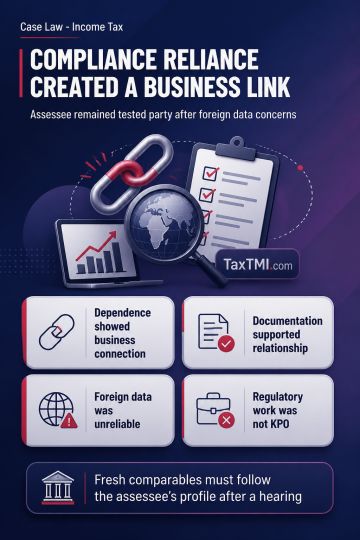
Business dependence on regulatory affairs and compliance processes established an associated-enterprise relationship, which was sustained because the relationship had also been accepted in transfer-pricing documentation. Foreign associated-enterprise selection as the tested party was rejected where reliable foreign comparable data was not readily accessible and geographical and economic conditions differed; the assessee was retained as the tested party. Domain-specific regulatory affairs services were not treated as KPO services merely by reference to the Rule 10TA definition, and comparables from diverse R&D, engineering, IT, advertising and gaming activities were unsuitable. Fresh benchmarking and comparable selection were directed in line with the assessee's FAR profile after a hearing opportunity.

Topics

Acts Income Tax