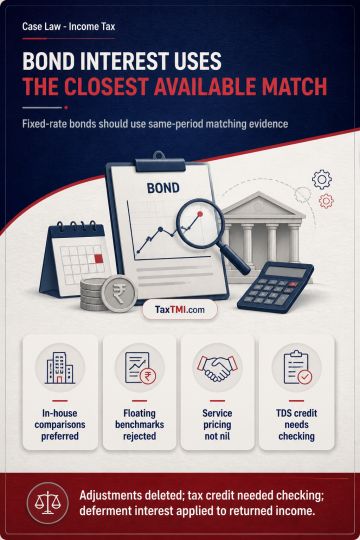
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916