Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
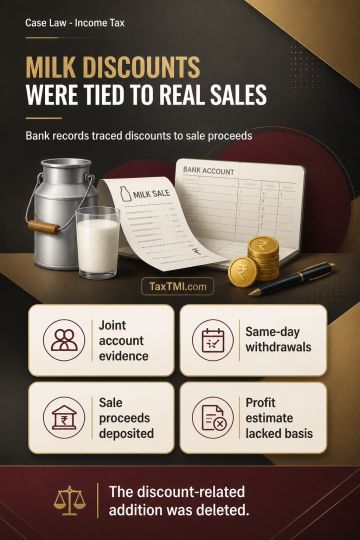
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918