Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
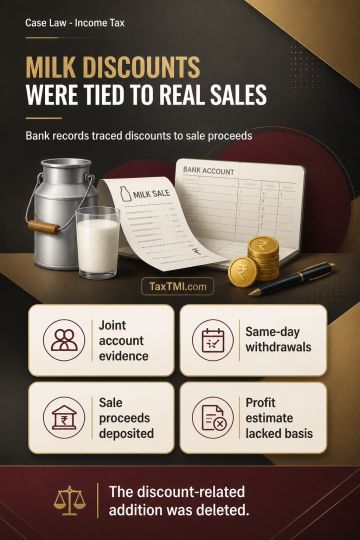
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918