Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
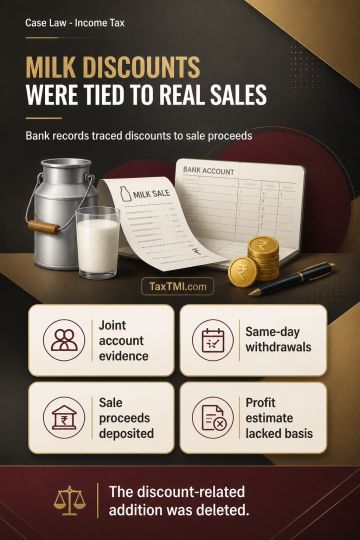
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Trade and quantity discounts received by a milk resale agent constituted an explained source of income where bank statements showed that sale proceeds were deposited into a joint account with the dairy and withdrawn by the dairy on the same day. Treating those discounts as unexplained money was therefore unwarranted. Profit estimation at 70% of the total discounts, with only 30% allowed for storage and distribution expenses, lacked a proper basis. The addition relating to the discounts was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918