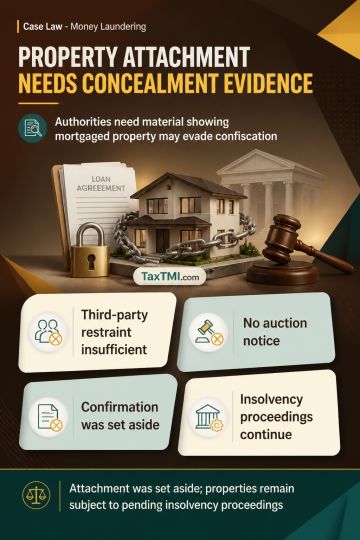
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
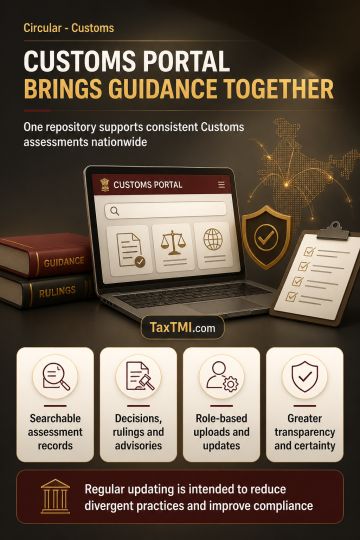
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
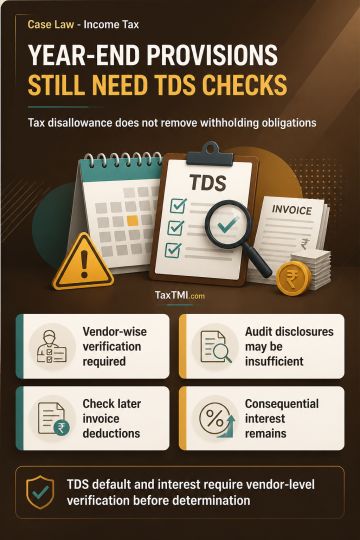
TDS obligations on year-end expense provisions remain independent of any suo motu disallowance for non-deduction of tax. Such disallowance is intended to secure compliance with withholding requirements but does not eliminate liability for TDS default or consequential interest. General tax-audit disclosures, without vendor-wise details, credited amounts, accounting treatment, and the basis of provisions, cannot establish the nature or extent of TDS liability. Verification is required of subsequent invoice-based TDS deduction, reversal of ad hoc provisions, and entries claimed to be outside TDS requirements before determining default and consequential liability.
TDS obligations on year-end expense provisions remain independent of any suo motu disallowance for non-deduction of tax. Such disallowance is intended to secure compliance with withholding requirements but does not eliminate liability for TDS default or consequential interest. General tax-audit disclosures, without vendor-wise details, credited amounts, accounting treatment, and the basis of provisions, cannot establish the nature or extent of TDS liability. Verification is required of subsequent invoice-based TDS deduction, reversal of ad hoc provisions, and entries claimed to be outside TDS requirements before determining default and consequential liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915