Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
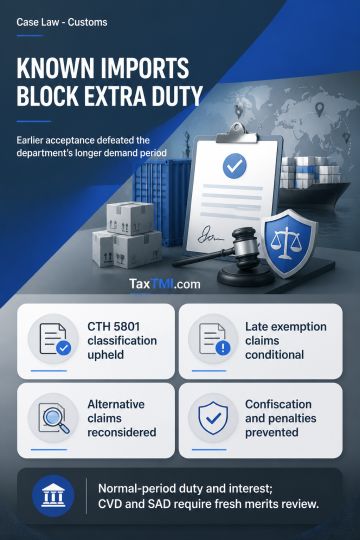
Departmental knowledge of identical imports and prior acceptance of the declared classification negated suppression and intent to evade duty; the extended-period duty demand and related interest were therefore set aside. Woven warp cut-pile fabrics were correctly classified under CTH 5801 because that specific heading for woven pile fabrics prevailed over general silk or rayon fabric headings, irrespective of rayon predominance. Exemptions not claimed at clearance may be claimed at adjudication, absent fraud, if substantive and procedural conditions are met; the alternative CVD and SAD claims require fresh merits determination, with any duty and interest confined to the normal period. Prior departmental acceptance also excluded deliberate misclassification, preventing confiscation and penalties.
Departmental knowledge of identical imports and prior acceptance of the declared classification negated suppression and intent to evade duty; the extended-period duty demand and related interest were therefore set aside. Woven warp cut-pile fabrics were correctly classified under CTH 5801 because that specific heading for woven pile fabrics prevailed over general silk or rayon fabric headings, irrespective of rayon predominance. Exemptions not claimed at clearance may be claimed at adjudication, absent fraud, if substantive and procedural conditions are met; the alternative CVD and SAD claims require fresh merits determination, with any duty and interest confined to the normal period. Prior departmental acceptance also excluded deliberate misclassification, preventing confiscation and penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916