Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
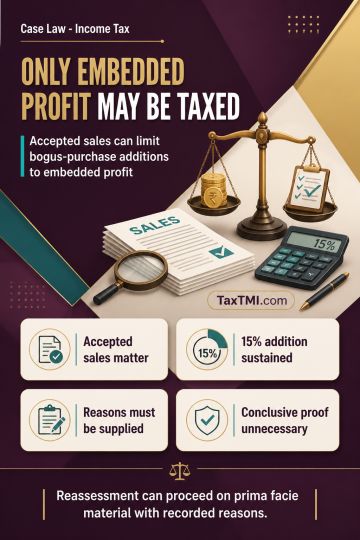
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Restricted second-hand parts of capital goods imported without...
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import provision.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Restricted second-hand parts of capital goods imported without the required authorisation may be confiscated, but restriction alone does not justify absolute confiscation without specific reasons. Where the goods are restricted rather than prohibited, redemption on payment of fine remains available. Penalty for importing such goods was treated under the provision applicable to improper import; enhancement under a separate provision operating on different premises was not sustainable. The appellate order directing absolute confiscation and enhancing the penalty was set aside, while the original order allowing redemption and imposing the applicable import penalty was restored.
Restricted second-hand parts of capital goods imported without the required authorisation may be confiscated, but restriction alone does not justify absolute confiscation without specific reasons. Where the goods are restricted rather than prohibited, redemption on payment of fine remains available. Penalty for importing such goods was treated under the provision applicable to improper import; enhancement under a separate provision operating on different premises was not sustainable. The appellate order directing absolute confiscation and enhancing the penalty was set aside, while the original order allowing redemption and imposing the applicable import penalty was restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916