Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Restricted second-hand parts of capital goods imported without...
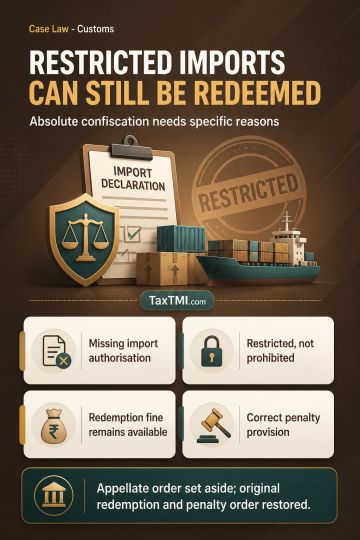
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import provision.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Restricted second-hand parts of capital goods imported without the required authorisation may be confiscated, but restriction alone does not justify absolute confiscation without specific reasons. Where the goods are restricted rather than prohibited, redemption on payment of fine remains available. Penalty for importing such goods was treated under the provision applicable to improper import; enhancement under a separate provision operating on different premises was not sustainable. The appellate order directing absolute confiscation and enhancing the penalty was set aside, while the original order allowing redemption and imposing the applicable import penalty was restored.
Restricted second-hand parts of capital goods imported without the required authorisation may be confiscated, but restriction alone does not justify absolute confiscation without specific reasons. Where the goods are restricted rather than prohibited, redemption on payment of fine remains available. Penalty for importing such goods was treated under the provision applicable to improper import; enhancement under a separate provision operating on different premises was not sustainable. The appellate order directing absolute confiscation and enhancing the penalty was set aside, while the original order allowing redemption and imposing the applicable import penalty was restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI