Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
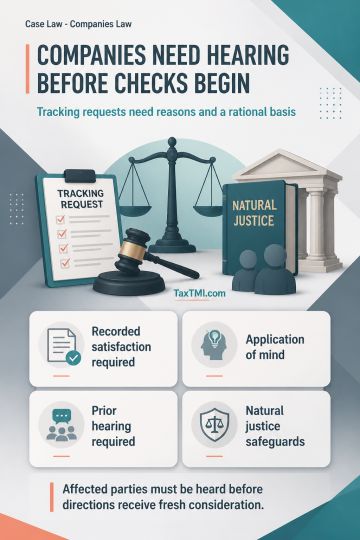
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Section 213(b) requires recorded satisfaction, reasons showing application of mind, and a reasonable opportunity of hearing before an investigation into company affairs, or preliminary steps towards it, is directed. Requests to external investigative agencies for tracking information at the initial stage cannot proceed without a rational basis, compliance with those statutory conditions, and prior hearing of affected parties. Directions issued without these safeguards are contrary to natural justice and require fresh consideration after hearing the affected party.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920