Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
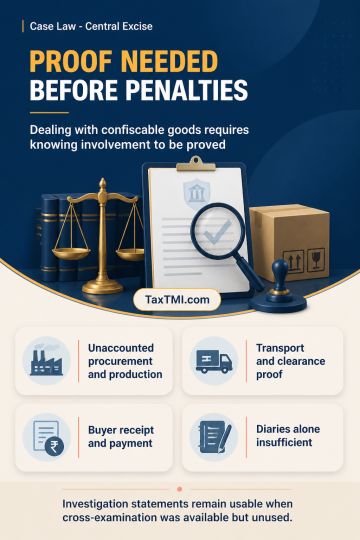
Penalty under Rule 26 for dealing in goods liable to confiscation requires proof that the person acquired, possessed or dealt with excisable goods knowing or believing them to be liable to confiscation. Allegations of clandestine removal require affirmative evidence across the production and supply chain, including unaccounted procurement and production, transport and clearance, identified buyers' receipt, and unaccounted consideration; recovered diaries or notepads alone do not establish their contents as true. Statements recorded during investigation may be relied on where examination and cross-examination opportunities were provided but not used, without violating natural justice.
Penalty under Rule 26 for dealing in goods liable to confiscation requires proof that the person acquired, possessed or dealt with excisable goods knowing or believing them to be liable to confiscation. Allegations of clandestine removal require affirmative evidence across the production and supply chain, including unaccounted procurement and production, transport and clearance, identified buyers' receipt, and unaccounted consideration; recovered diaries or notepads alone do not establish their contents as true. Statements recorded during investigation may be relied on where examination and cross-examination opportunities were provided but not used, without violating natural justice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918