Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
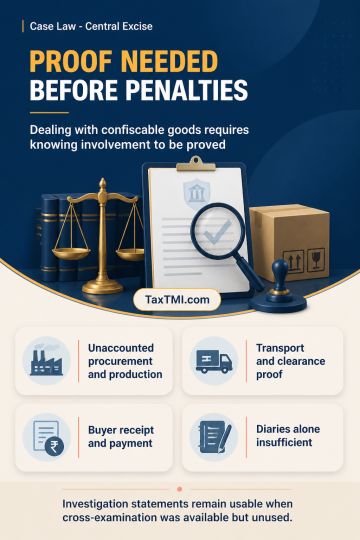
Penalty under Rule 26 for dealing in goods liable to confiscation requires proof that the person acquired, possessed or dealt with excisable goods knowing or believing them to be liable to confiscation. Allegations of clandestine removal require affirmative evidence across the production and supply chain, including unaccounted procurement and production, transport and clearance, identified buyers' receipt, and unaccounted consideration; recovered diaries or notepads alone do not establish their contents as true. Statements recorded during investigation may be relied on where examination and cross-examination opportunities were provided but not used, without violating natural justice.
Penalty under Rule 26 for dealing in goods liable to confiscation requires proof that the person acquired, possessed or dealt with excisable goods knowing or believing them to be liable to confiscation. Allegations of clandestine removal require affirmative evidence across the production and supply chain, including unaccounted procurement and production, transport and clearance, identified buyers' receipt, and unaccounted consideration; recovered diaries or notepads alone do not establish their contents as true. Statements recorded during investigation may be relied on where examination and cross-examination opportunities were provided but not used, without violating natural justice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916