Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
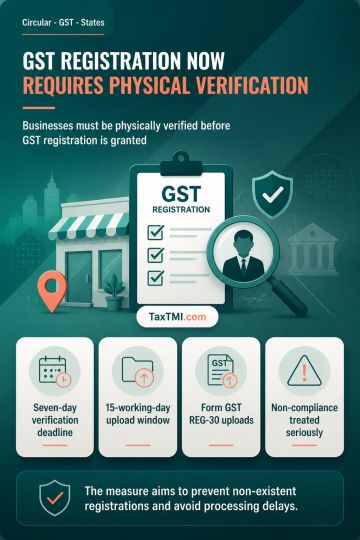
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Page of 4920
Press 'Enter' after typing page number.
1521 to 1540 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Alternate statutory remedy was central to the GST challenge...
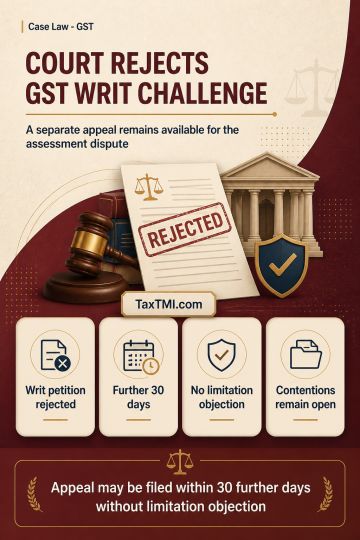
Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing period.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Alternate statutory remedy was central to the GST challenge against an assessment order issued under Section 74 of the Uttar Pradesh GST Act for financial year 2018-19, raising issues of the Section 6(2)(b) bar and proper-officer jurisdiction. The High Court rejected the writ petition while allowing recourse to the statutory appeal. The Supreme Court declined to entertain the special leave petition but allowed a further 30 days to file the appeal without a limitation objection. All contentions, including the pre-deposit issue in light of payment under parallel Central Act proceedings, remain open.
Alternate statutory remedy was central to the GST challenge against an assessment order issued under Section 74 of the Uttar Pradesh GST Act for financial year 2018-19, raising issues of the Section 6(2)(b) bar and proper-officer jurisdiction. The High Court rejected the writ petition while allowing recourse to the statutory appeal. The Supreme Court declined to entertain the special leave petition but allowed a further 30 days to file the appeal without a limitation objection. All contentions, including the pre-deposit issue in light of payment under parallel Central Act proceedings, remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920