Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Page of 4920
Press 'Enter' after typing page number.
201 to 220 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
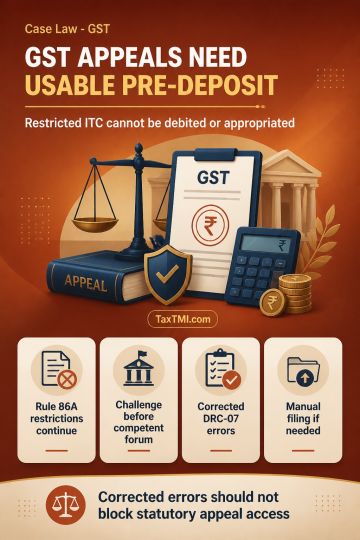
Blocked input tax credit subject to a subsisting Rule 86A restriction cannot be debited, treated as payment, or appropriated towards the mandatory pre-deposit for a GST appeal. The restriction may be challenged or sought to be modified before the competent forum. An erroneous FORM GST DRC-07 attributable to the adjudicating authority, once rectified, should not deprive the taxpayer of the statutory appellate remedy. Electronic filing of the appeal must be enabled, with manual filing available if portal issues persist, subject to compliance with the prescribed pre-deposit.
Blocked input tax credit subject to a subsisting Rule 86A restriction cannot be debited, treated as payment, or appropriated towards the mandatory pre-deposit for a GST appeal. The restriction may be challenged or sought to be modified before the competent forum. An erroneous FORM GST DRC-07 attributable to the adjudicating authority, once rectified, should not deprive the taxpayer of the statutory appellate remedy. Electronic filing of the appeal must be enabled, with manual filing available if portal issues persist, subject to compliance with the prescribed pre-deposit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920