Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
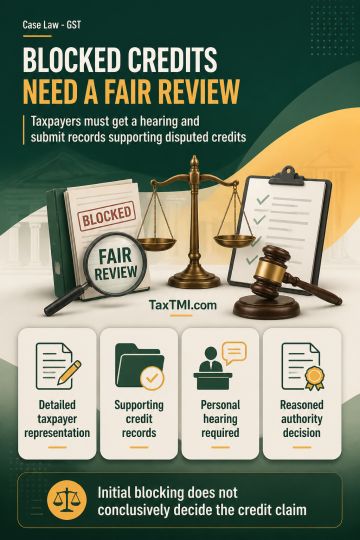
Blocking an Electronic Credit Ledger may be based on reasons to believe that input tax credit was fraudulently availed or is ineligible, including where suppliers are alleged to be non-existent or their registrations cancelled. Even where such statutory conditions are prima facie met, audi alteram partem requires a post-decisional hearing. The affected taxpayer must be allowed to submit a detailed representation and supporting records to substantiate the credit claim. The competent authority must grant a personal hearing and issue a reasoned, speaking determination independently of prior observations, without merits being conclusively adjudicated at the blocking stage.
Blocking an Electronic Credit Ledger may be based on reasons to believe that input tax credit was fraudulently availed or is ineligible, including where suppliers are alleged to be non-existent or their registrations cancelled. Even where such statutory conditions are prima facie met, audi alteram partem requires a post-decisional hearing. The affected taxpayer must be allowed to submit a detailed representation and supporting records to substantiate the credit claim. The competent authority must grant a personal hearing and issue a reasoned, speaking determination independently of prior observations, without merits being conclusively adjudicated at the blocking stage.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI