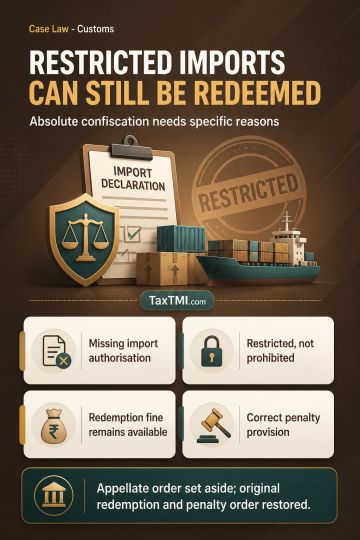
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
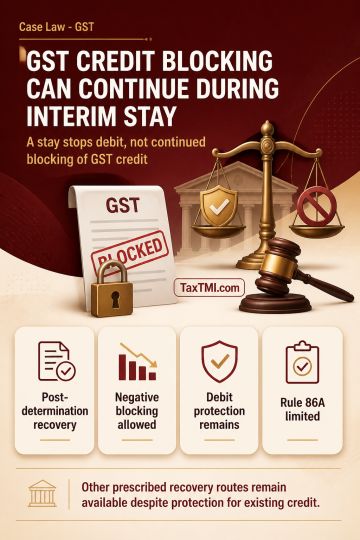
Post-determination recovery of determined GST dues may include blocking, including negative blocking, of the electronic credit ledger. The interim protection against recovery restricts only debit of credit already lying in the ledger towards recovery; it does not invalidate or suspend a prior ledger-blocking order. Recovery powers extend to prescribed modes involving money or goods under the proper officer's control, third-party recovery, distraint and sale of assets, and assistance from revenue authorities. Rule 86A governs provisional pre-determination blocking and does not limit post-determination recovery action. Electronic credit ledger blocking therefore remains permissible, subject to the protection against debit of available credit during the interim stay.
Post-determination recovery of determined GST dues may include blocking, including negative blocking, of the electronic credit ledger. The interim protection against recovery restricts only debit of credit already lying in the ledger towards recovery; it does not invalidate or suspend a prior ledger-blocking order. Recovery powers extend to prescribed modes involving money or goods under the proper officer's control, third-party recovery, distraint and sale of assets, and assistance from revenue authorities. Rule 86A governs provisional pre-determination blocking and does not limit post-determination recovery action. Electronic credit ledger blocking therefore remains permissible, subject to the protection against debit of available credit during the interim stay.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916