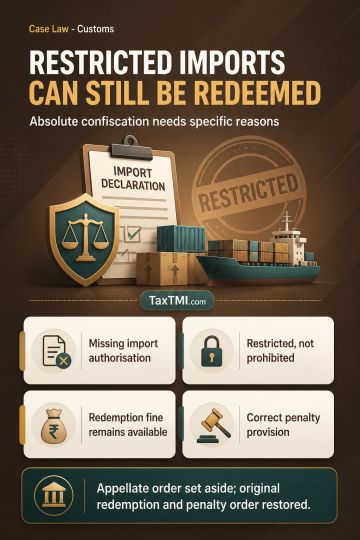
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Rectification of patent errors in GST proceedings is confined to errors apparent on the face of the record and cannot be used to revisit an original determination on under-declared ineligible input tax credit. Where no apparent error is established and supporting documents were not submitted, rejection of a rectification application remains undisturbed. The taxpayer may challenge the original determination independently in accordance with law, rather than seek substantive reconsideration through rectification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916