Bail conditions in customs-duty evasion investigation permit continued inquiry while addressing evidence-tampering concerns through procedural safegua...
GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Page of 4921
Press 'Enter' after typing page number.
1761 to 1780 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
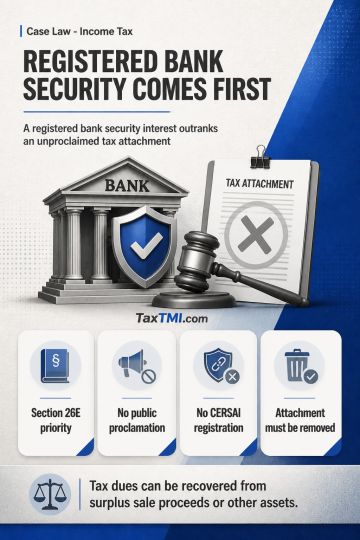
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921