Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
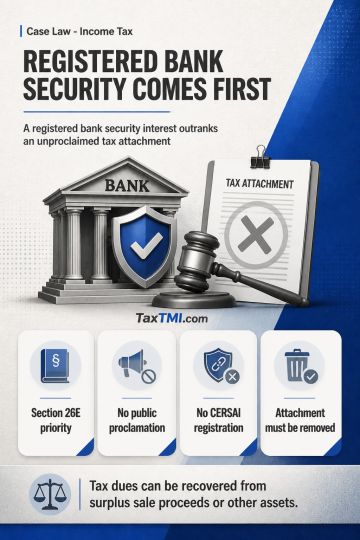
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918