Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
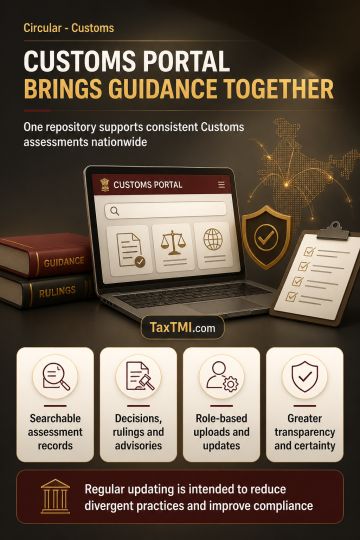
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
Section 110(2) requires release of detained gold only if the Section 124 show-cause notice is not issued within the prescribed period, including any validly extended period. Issuance of written notice before expiry of the extended period prevents a release claim based solely on expiry of the initial period. Accordingly, no release direction follows where the petition is filed while the extended period subsists and the notice is timely issued. Questions concerning the extension's validity and communication, waiver of notice or hearing, and evidentiary value of statements remain for adjudication in accordance with law.
Section 110(2) requires release of detained gold only if the Section 124 show-cause notice is not issued within the prescribed period, including any validly extended period. Issuance of written notice before expiry of the extended period prevents a release claim based solely on expiry of the initial period. Accordingly, no release direction follows where the petition is filed while the extended period subsists and the notice is timely issued. Questions concerning the extension's validity and communication, waiver of notice or hearing, and evidentiary value of statements remain for adjudication in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916