Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
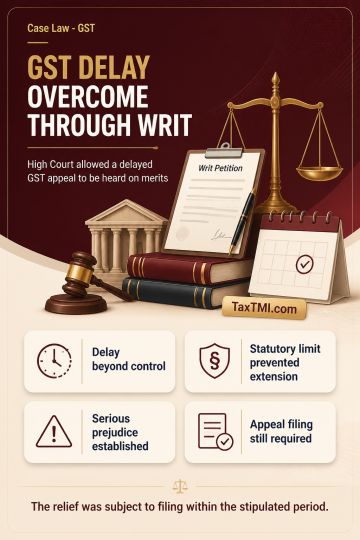
Condonation of delay in filing a GST appeal was granted in writ jurisdiction despite the Appellate Authority's statutory inability to extend the limitation under section 107 of the RGST/CGST Act. Delay attributable to circumstances beyond the petitioner's control, coupled with the grave prejudice arising from refusal of merits review, justified relief. The High Court directed the Appellate Authority to entertain and decide the appeal on merits, subject to filing within the stipulated period.
Condonation of delay in filing a GST appeal was granted in writ jurisdiction despite the Appellate Authority's statutory inability to extend the limitation under section 107 of the RGST/CGST Act. Delay attributable to circumstances beyond the petitioner's control, coupled with the grave prejudice arising from refusal of merits review, justified relief. The High Court directed the Appellate Authority to entertain and decide the appeal on merits, subject to filing within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918